Novo Nordisk Price Target Rises to $80 as Oral Wegovy Surpasses 3 Million Prescriptions
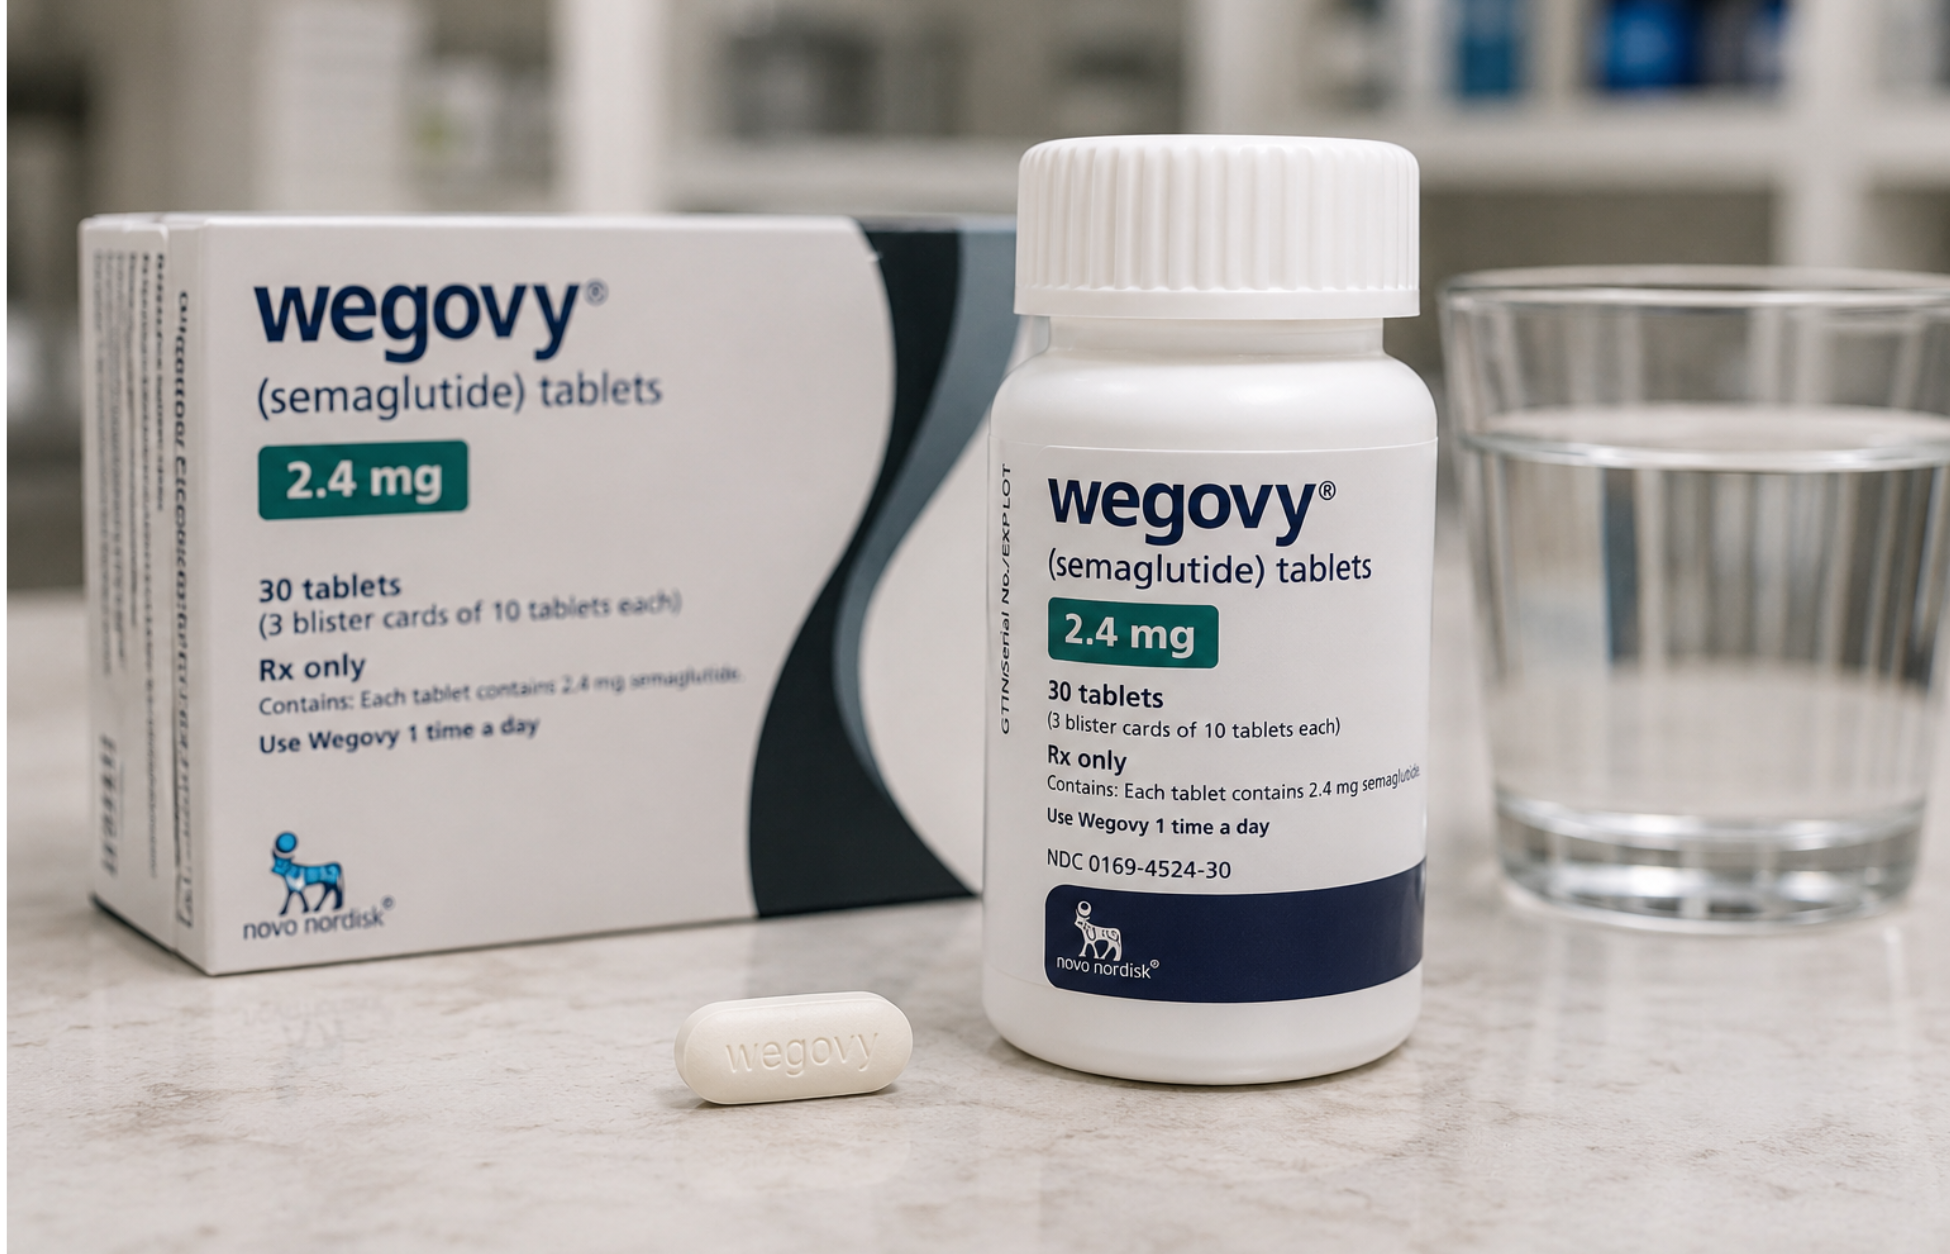
Novo Nordisk received an upgraded price target of $80, while market analysts assigned the stock a Modest Buy rating. The strategic revision reflects rapid uptake of oral Wegovy, the company’s novel tablet formulation of semaglutide. In view of this, physicians wrote more than 3 million prescriptions within five months of product launch. Consequently, this remarkable volume signals substantial market demand for oral metabolic therapies.
Notably, 80 percent of oral Wegovy users had never previously received a GLP-1 medication. In light of this, the tablet formulation expands the market rather than cannibalizing existing injectable treatments. Instead, the convenient oral option successfully draws an entirely new patient population into therapeutic care. Furthermore, oral administration removes a primary hurdle for individuals who experience needle aversion or logistical inconvenience.
Semaglutide, the active compound in Wegovy, belongs to the glucagon-like peptide-1 receptor agonist class. To be precise, the active compound mimics a naturally occurring peptide hormone that regulates appetite and blood glucose levels. Furthermore, the Food and Drug Administration approved semaglutide for chronic weight management in qualified adult populations. Separately, distinct semaglutide formulations also carry federal approval for type 2 diabetes management under the Ozempic brand.
Along with this, financial analysts project that oral Wegovy could generate between $12 billion and $15 billion in annual gross profit. This realistic financial projection accounts for anticipated pricing dynamics, manufacturing costs, and expected patient volume expansion. Consequently, the tablet formulation represents a crucial growth driver within the broader obesity treatment portfolio. Therefore, the product positions the enterprise strongly against industry competitors and alternative therapeutic formulations.
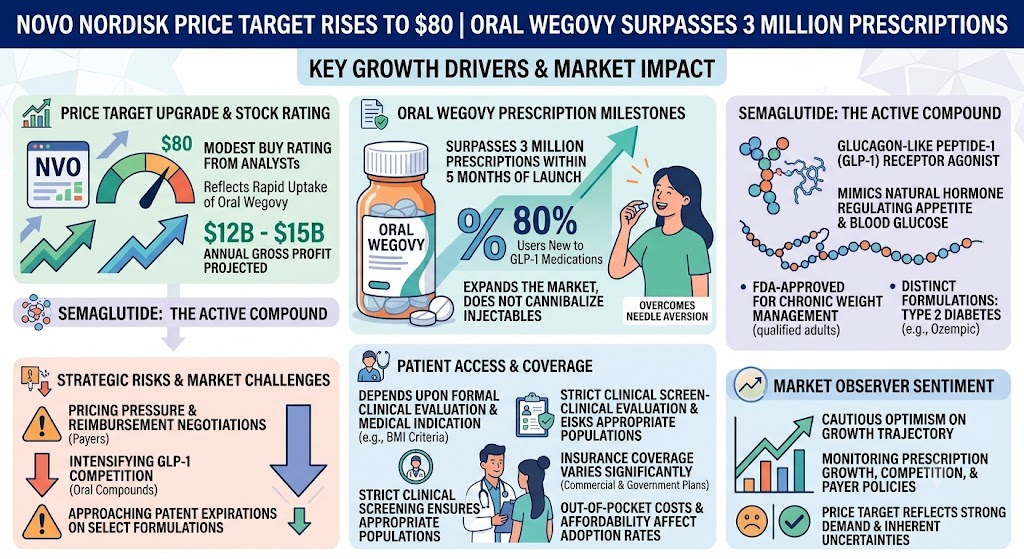
Nevertheless, the projected commercial growth trajectory carries identifiable strategic risks over the intermediate horizon. Pricing pressure remains a persistent challenge as commercial insurance payers negotiate aggressive reimbursement terms and formulary positioning. Furthermore, competition within the GLP-1 category continues to intensify as rival pharmaceutical manufacturers develop competing oral compounds. Accordingly, approaching patent expirations on select semaglutide formulations pose an eventual threat to long-term market exclusivity.
Given this, patient access to oral Wegovy depends entirely upon formal clinical evaluation and appropriate medical indication. Licensed prescribers must confirm that individuals meet body mass index criteria or exhibit qualifying comorbid conditions. Building on this, strict clinical screening ensures that treatment targets appropriate populations defined during regulatory review trials. Thus, professional oversight maintains compliance with approved therapeutic guidelines across all treatment settings.
Insurance coverage for oral Wegovy varies significantly across individual healthcare plans and commercial benefit designs. Moreover, out-of-pocket costs remain a substantial economic consideration for a broad segment of prospective patients. Meanwhile, the Centers for Medicare and Medicaid Services maintains evolving coverage policies regarding dedicated obesity medications. As a result, patient affordability continues to influence overall therapy adoption rates and long-term treatment adherence.
In light of these factors, market observers maintain cautious optimism regarding the corporate growth trajectory. The enterprise’s ability to maintain prescription growth while navigating competitive pressures will determine final financial outcomes. Given this, industry analysts continually monitor quarterly prescription volume data alongside evolving payer coverage policies. Hence, the revised $80 price target reflects strong current market demand alongside inherent industry uncertainties.